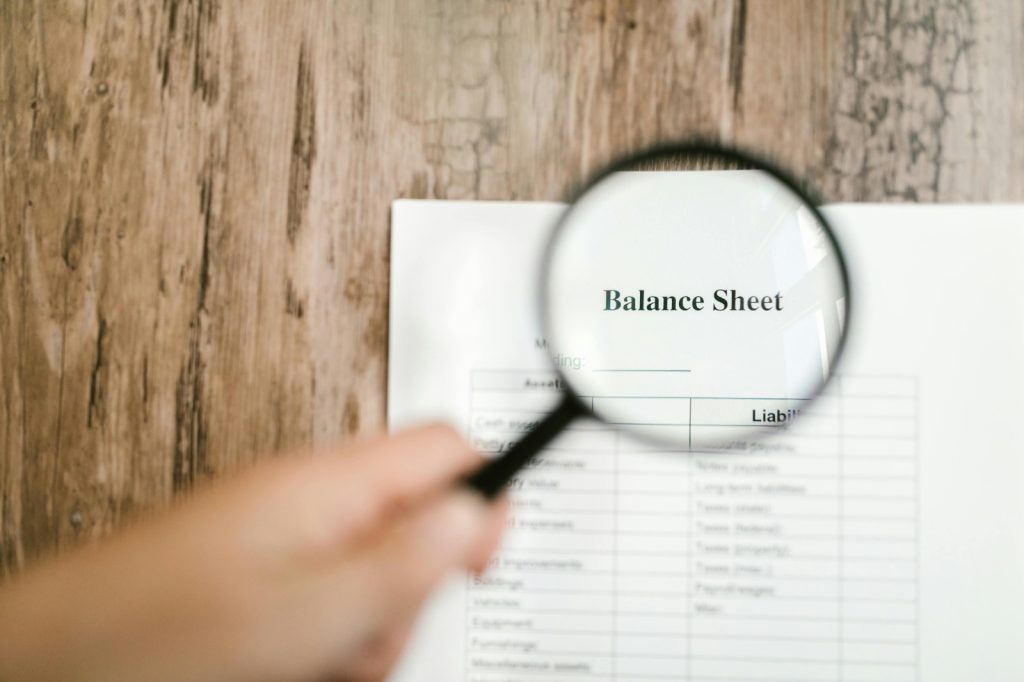
Understand a balance sheet it can feel like reading an airplane dashboard: many names, many figures, and the constant doubt of what it means for something to be “good” or “bad.”.
The good news is that the balance sheet is not made just for “accounting experts”; it is made to answer simple questions for anyone: What does the company own, what does it owe, and what part of that actually belongs to the owners?
When you look at the balance sheet through that lens, it stops being intimidating and becomes a practical tool for making better decisions.
At Valoriza we work with companies in valuations, mergers and acquisitions (M&A) and strategic consulting, and the balance sheet is usually the first snapshot we review to understand a company and its financial health. Because, before talking about growth, investment, or sales, we must have clarity on the foundation: assets, liabilities, and equity.
This article is a step-by-step guide designed for non-financial people (founders, managers, commercial, or operational teams). You don't need to memorize accounting standardsjust learning to read the balance sheet for what it is, a photograph of the company on a specific date.
What is the balance sheet and what is its purpose
The balance sheet (or “statement of financial position”) is a snapshot of the company on a given day. Unlike the income statement (which tells a movie about a company: sales, costs, and profit over a period), the balance sheet answers: “What does the company look like today?” That is why it always comes with a date: “as of December 31,” “as of the close of January,” “as of June 30.”.
That photo is organized into three major blocks: Assets, Liabilities and Equity. And everything revolves around an equation that you will see repeated everywhere: Assets = Liabilities + Equity. In simple words: everything the company has (assets) is financed either by third parties (liabilities: debt and accounts payable) or by the owners (equity: capital and retained earnings).
What is it for? To make decisions with less intuition and more evidence. A balance sheet allows you to identify whether the company is “financing” itself through suppliers, if it has enough cash to operate, if it is overly in debt, if it is tying up capital in inventory, or if it is accumulating profits that can be reinvested. And when valuation or sale is discussed, the balance sheet helps to understand risks, working capital needs, and financial sustainability.
The key equation: Assets = Liabilities + Equity
This equation isn't just theory—it's a way of thinking. If a company has $100 in assets, that money necessarily came from somewhere. It may have come from debt (liabilities) or from contributions/retained earnings (equity). The balance sheet is, at its core, a permanent “sources and uses” statement.
To make it intuitive, Imagine a company that has $100 in cash and equipment. If it owes $40 to the bank and $10 to suppliers, its equity (what “remains” for the owners) is $50. It is not that equity is a bank account; it is the residual book value: if you liquidated everything at book value and paid all debts, that would belong to the owners.
The power of this equation is that it forces you to look at the changes. If the asset goes up, did it go up because debt increased? Or because profits were generated? If cash goes down, did it go down because you paid debt, because you invested, or because the business is not generating cash?
Learning to “read movement” from this equation is the first step to using the balance sheet as a management tool, not as a formal report.
Step 1: locate the date and understand that it is a “photo”
Before looking at numbers, look at the header. It should say “as of” a date. That detail is essential, because many confusions come from comparing balance sheets without considering seasonality or accounting closing periods.
A balance sheet as of December 31 can look very different from one in August due to normal business reasons: seasonal inventories, concentrated collections, annual payments, etc.
Consider also what happened around that date. If the company raised capital at the end of the month, cash flow may look “inflated.” If it made a large inventory purchase right before the close, it might look like the company “has a lot of assets,” but in reality, it has cash tied up in stock.
The balance sheet doesn't lie, but it can be misinterpreted if it is not contextualized.
Finally, remember that the balance is “a cut”. Many companies make mistakes by making long-term decisions based on a single snapshot. The right approach is to look at the balance sheet movie: comparing several months or quarters to understand trends, not just a single closing period.
Step 2: Understand the order — liquidity and exigibility
Balance sheets are usually ordered by asset liquidity (how quickly they are converted into cash) and why liability maturity (how soon you need to pay them). That's why you'll see typical divisions: Current assets short term and non-current (long term); the same for liabilities.
This structure allows you to answer a very specific question: can the company meet its commitments for the next 12 months with the resources that will also move within the next 12 months? That is the basis of liquidity, and it is one of the reasons why the balance sheet is key to understanding health.
In the real world, “current” doesn't always mean “easy.” An account receivable can be current, but if it's uncollectible or paid late, it doesn't help cover obligations. Inventory can be current, but if it turns over slowly, it doesn't help either. That's why order is a clue, not a guarantee: it guides you on what to examine closely.
Step 3: read assets as “what the company controls”
The Assets are resources controlled by the company and from which it expects to obtain future economic benefits. The keyword is “control”: not everything the company “uses” appears as an asset, and not every asset is “good.”.
An asset can represent efficiency (productive equipment) or inefficiency (stagnant inventory, overdue accounts receivable).
At operating companies, assets are usually concentrated in cash, accounts receivable, inventories, fixed assets (property, plant, and equipment), and sometimes intangibles (software, licenses, developments).
In service companies, it is common to see less inventory and more accounts receivable. In startups, you will sometimes see high cash from funding rounds and low fixed assets.
A typical mistake for non-finance people is to assume that “more assets = better company.” Not necessarily. More accounts receivable can mean more sales, yes, but it can also mean worse collection.
More inventory can mean preparation for demand, or it can mean overstock. The balance sheet doesn't give the diagnosis by itself; it shows you “where to look.”.
Step 4: separate current and non-current assets (and what each one tells you)
The current assets are those that should be converted into cash within 12 months (or the operating cycle). Cash and banks, accounts receivable, inventories, and other current assets (advances, recoverable taxes, etc.) usually appear here. This block is the heart of working capital: what keeps the business running day-to-day.
The box is obvious, but it is important to look at its relationship with the upcoming obligations. The accounts receivable They talk to you about credit sales and discipline of collection. The iinventories tell you about the operating modelif you buy earlier, if you produce in batches, if you depend on imports, and how well you manage turnover.
At strategic consulting, when seeking to create value, many times the first quick win“ it's here: get paid faster, optimize stock, negotiate better terms.
The non-current assets are longer-term resources: equipment, machinery, offices, vehicles, long-term investments, intangibles. These assets are usually related to productive capacity and competitive advantage.
But they can also hide rigidity: too much investment in underutilized assets can reduce returns and pressure cash flow. That is why it is best to read them with one question: are these assets helping to generate revenue and margin, or are they a burden?
Step 5: understand liabilities as “what the company owes”
The Liabilities are present obligationsbank debts, accounts payable to suppliers, taxes, salaries payable, accrued rent, etc. Here It is a good idea to take a myth testhaving liabilities is not bad by definition. Debt and supplier credit are financing tools.
The relevant question is whether the company can pay them without suffocating its operations and whether they are aligned with the business's cash generation.
In the short term, liabilities tell you about liquidity pressureIf there are many obligations coming due soon, the company needs cash or refinancing. In the long run, liabilities tell you about capital structurehow much leverage are you using to grow and how does that affect risk.
When evaluate a company for M&A, the debt profile and contingencies is a critical part of the analysis.
An important point is that not all liabilities are “bank debt”. Many companies unintentionally finance themselves through suppliers (accounts payable).
That can be efficient if it is part of the model (good terms, good relationship), or it can be a sign of stress if unpaid debts or forced renegotiations accumulate. The balance sheet gives you the first indication.
Step 6: separate current and non-current liabilities (and why it matters)
The current liabilities are those that mature within 12 months: suppliers, taxes payable, payroll, short-term debt installments, etc. This block is what directly “fights” with current assets. That is why when someone talks about “liquidity,” deep down they are comparing these two worlds.
The Non-current liabilities are usually long-term debts., financial leases, deferred liabilities. They do not pressure immediate cash flow in the same way, but they do affect the risk profile and flexibility. A A company can have good liquidity today, but being burdened with long-term debt with strict covenants that will limit future decisions.
A practical read: if your current liabilities are growing faster than your current assets, you are probably funding operations with short-term liabilities. A veces eso es parte de la estrategia, pero si se vuelve crónico puede indicar falta de generación de caja o capital de trabajo mal gestionado.
Paso 7: Entiende el patrimonio — lo que “realmente queda” para los dueños
The patrimonio representa el interés residual de los dueños en la empresa, después de restar pasivos a activos. Aquí suelen aparecer cuentas como capital aportado, reservas, resultados acumulados y resultado del ejercicio. Este bloque es clave para entender si el negocio está construyendo valor con el tiempo o si se está “comiendo” su base.
En términos simples, si el patrimonio crece de forma sana, suele ser porque la empresa generó utilidades y las retuvo (o porque recibió aportes). Si el patrimonio se deteriora, puede ser por pérdidas, retiros, dividendos altos, o ajustes contables relevantes.
Cuando el patrimonio se vuelve bajo o negativo, la empresa entra en una zona delicada: puede operar, sí, pero con menos margen de maniobra y mayor riesgo percibido por bancos y proveedores.
También conviene entender una distinción: patrimonio contable no es lo mismo que “valor de mercado”. El patrimonio contable depende de criterios de reconocimiento y medición (por ejemplo, activos fijos al costo menos depreciación). El valor de mercado depende de la capacidad futura de generar flujos y del riesgo.
At valuations, esa diferencia es central: una empresa puede tener patrimonio contable bajo y aun así valer mucho (si genera caja); o lo contrario.
Paso 8: el “paso a paso” para leer cualquier balance en 10 minutos
First, verifica si la ecuación cuadra: activos igual a pasivos más patrimonio. Suena básico, pero te da confianza en que estás leyendo una estructura coherente. Luego, mira la composición: ¿qué pesa más, caja, cuentas por cobrar, inventario, activos fijos? Ese “mix” cuenta la historia del modelo de negocio.
Después, baja a la liquidez: compara activos corrientes contra pasivos corrientes. Si la empresa tiene más activos corrientes que obligaciones de corto plazo, en principio tiene colchón. Si está al revés, hay presión. A continuación, revisa de dónde viene la financiación: ¿predomina deuda bancaria, proveedores, o patrimonio?
Finally, hazte dos preguntas de gestión: (1) ¿qué cuentas están creciendo y por qué? y (2) ¿qué cuentas son “calidad” y cuáles son “ruido”? Calidad es caja real, cuentas por cobrar sanas, inventario rotando, activos productivos. Ruido es caja momentánea por un evento único, cuentas por cobrar atrasadas, stock muerto, activos fijos subutilizados.
Errores comunes al interpretar un balance (y cómo evitarlos)
The primer error es leer el balance como si fuera un ranking: “más grande es mejor”. Una empresa con más activos no es necesariamente más saludable; puede estar más cargada de inventario lento o de cuentas por cobrar difíciles. En balances, el tamaño importa menos que la calidad y la estructura.
The segundo error es mezclar “utilidad” con “caja”. Puedes tener utilidades en el estado de resultados y, al mismo tiempo, tener poca caja, porque la utilidad puede estar “atrapada” en cuentas por cobrar o inventarios. El balance te ayuda a ver eso: si crece la utilidad pero también crecen cuentas por cobrar, la empresa está vendiendo más a crédito y no necesariamente cobrando más rápido.
The tercer error es no comparar. Un balance aislado puede engañar. La lectura correcta requiere tendencia: comparar al menos dos o tres períodos. Cuando haces eso, empiezas a ver patrones: estacionalidad, acumulación de deuda, cambios en capital de trabajo. Ese es el punto en que el balance deja de ser un documento contable y se vuelve una herramienta de decisión.
Cómo conecta el balance con decisiones reales de negocio
Si estás pensando en crecer, el balance te dice si tienes capacidad de financiar ese crecimiento. Muchas empresas crecen en ventas, pero se ahogan en capital de trabajo: necesitan financiar cuentas por cobrar e inventarios, y eso exige caja o deuda. Entender esa dinámica a tiempo evita crecimientos que comprometen la liquidez.
Si estás pensando en vender o buscar inversión, el balance es una de las primeras piezas que revisarán. No solo por los números, sino por señales de orden: conciliaciones, claridad de cuentas, consistencia de criterios, niveles de deuda y contingencias.
At M&A processes, una lectura fina del balance ayuda a anticipar preguntas durante el due diligence y a preparar la compañía para una conversación más sólida.
Y si estás gestionando el día a día, el balance te da un tablero de control silencioso: si suben demasiado las cuentas por cobrar, hay que ajustar cobranza; si el inventario se infla, hay que revisar compras y demanda; si los pasivos corrientes se disparan, hay que renegociar plazos o ajustar gastos; si la caja cae, hay que mirar ciclo de caja y no solo ventas.
Al final, el balance te obliga a mirar la empresa como sistema, no como una sola métrica.
Una forma simple de recordarlo
Si tuvieras que quedarte con una sola idea, que sea esta: el balance es una foto de qué tienes, qué debes y qué te pertenece. Los activos te muestran recursos; los pasivos, obligaciones; el patrimonio, el residual de los dueños.
Y el valor real de leerlo está en conectar esos números con decisiones: liquidez, riesgo, eficiencia operativa y estructura de financiamiento.
A medida que lo uses, vas a notar algo: no necesitas “ser financiero” para hacer buenas preguntas. De hecho, el mejor uso del balance no es recitar definiciones, sino detectar dónde hay tensión y dónde hay oportunidad.
Y cuando el balance se vuelve conversación habitual (no un documento que se mira una vez al año), la empresa toma decisiones con más claridad y menos sorpresa.